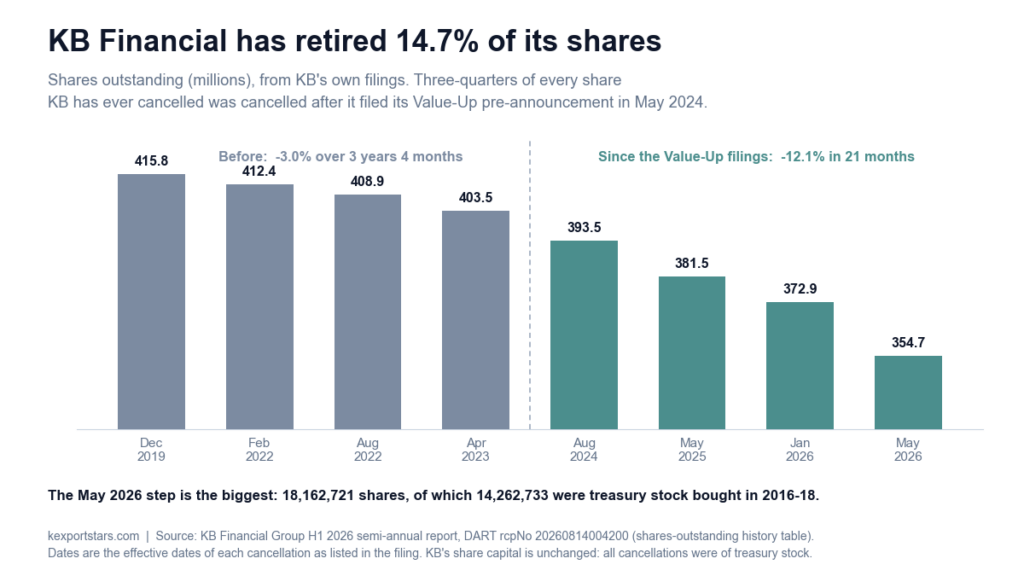
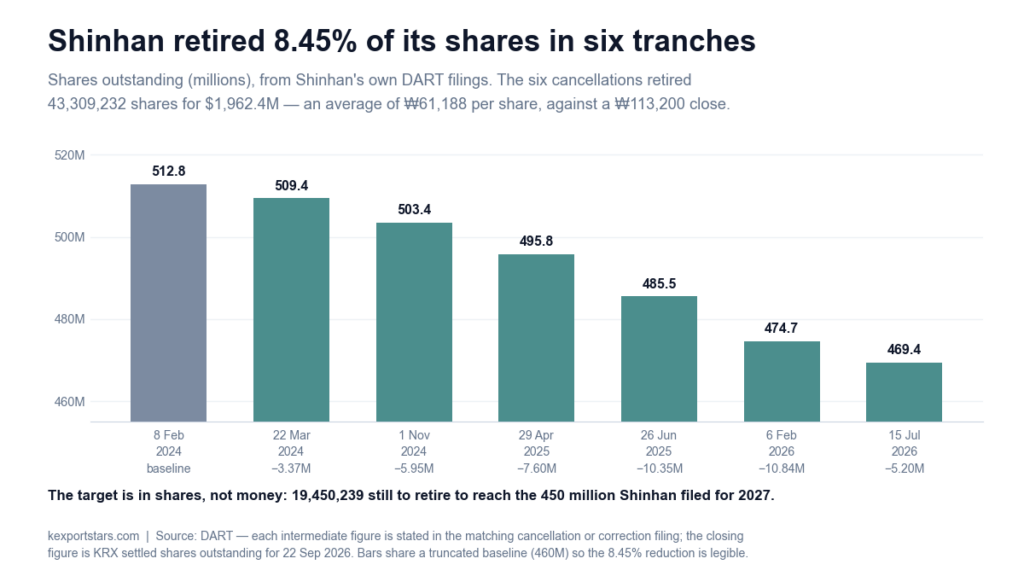
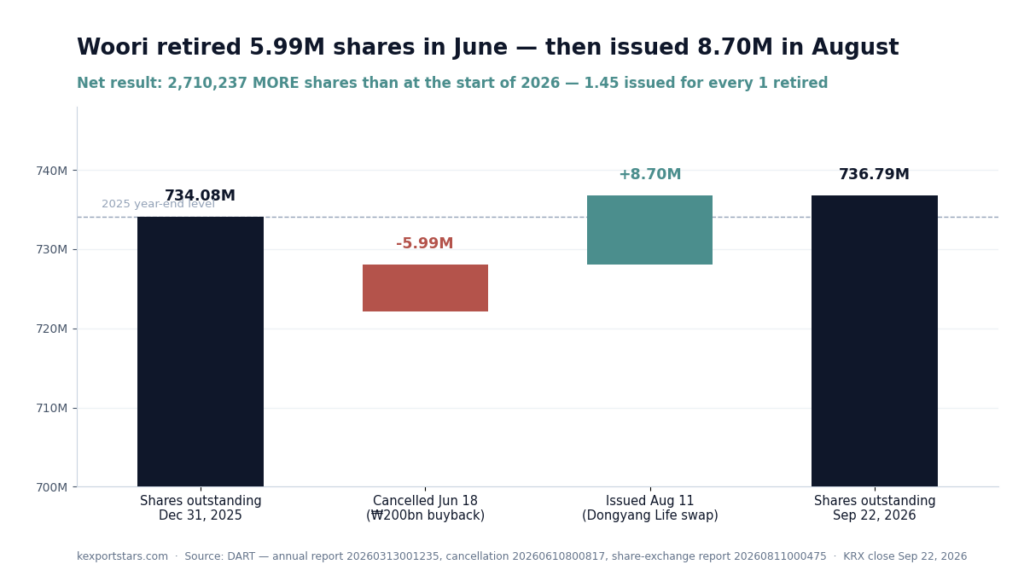
Korea has four giant financial holding companies. Three of them trade in New York. The fourth — the one that owns the country’s biggest foreign-exchange bank, earns more per share than two of its rivals, and pays the highest dividend of the three majors — has no U.S. line at all. Its filings are in Korean, its investor decks are in Korean, and the table that tells you the most interesting thing about it is buried deep inside a half-year report nobody translates. This is that table.
🔑 Key Takeaways
- Hana is the cheapest of Korea’s three largest banks on earnings. At ₩136,000 (~$100.71) on 22 September 2026 it trades at 9.8× FY2025 earnings against KB’s 11.4× and Shinhan’s 11.5×, and yields 3.0% against their 2.5% and 2.3%. Only Woori, the smallest of the big four, is cheaper. (Sources: KRX settled close, 22 Sep 2026; DART FY2025 annual report as amended — [기재정정]사업보고서 (2025.12), rcpNo 20260814004019.)
- Hana has bought back and permanently destroyed 9.75% of every share it has ever issued. 300,242,062 shares issued since inception, 29,272,152 cancelled, 270,969,910 listed today — the three numbers reconcile exactly. (Source: DART H1 2026 half-year report, rcpNo 20260814003800, plus the 26 Aug 2026 cancellation filings.)
- The buffer paying for that is thinning. Group loan-loss reserves covered 200.80% of substandard-and-below loans at their 4Q 2022 peak and 107.00% at 30 June 2026 — a 93.8-point fall, disclosed on the regulator’s basis as a 46-quarter series inside Hana’s own filing, with no commentary. Bad loans grew 52% over 18 months; reserves grew 17%. At 107.0% Hana has the lowest cover and the lowest CET1 ratio of Korea's big four. (Sources: DART H1 2026 half-year report, rcpNo 20260814003800, indicator-trend and soundness tables; peers from their own 14 Aug 2026 filings — see below for how each one is measured, because they are not measured identically.)
- Korea’s banks quietly unlocked $18.3bn of new dividend capacity in the first half of 2026. Hana, KB and Shinhan each converted capital surplus into distributable retained earnings — $5.5bn, $5.6bn and $7.3bn respectively. Woori had already done it a year earlier, at its March 2025 meeting, creating ₩3.0tn ($2.22bn) of distributable income — so all four have now used the same provision, and Woori used it first. None of it made the English-language wires. (Sources: each group’s AGM-result filing — Woori rcpNo 20250326802725 (26 Mar 2025), Hana rcpNo 20260324801626, Shinhan rcpNo 20260326802328, KB rcpNo 20260326803383 — read against each one’s consolidated balance sheet.)
- There is no controlling family. Hana’s three largest holders are Korea’s National Pension Service (8.90% of shares issued, or 9.14% of the shares that carry votes), BlackRock (7.22%) and Capital Group (5.63%); 73.44% of the voting stock sits with 161,982 minority holders. The chaebol-control story most foreign investors apply to Korea simply does not fit here — which makes the governance question a different one, not an absent one.
🏢 What Is Hana Financial Group, and What Does It Actually Sell?
Hana Financial Group is a Korean bank holding company that owns 14 direct financial subsidiaries and earns roughly nine out of every ten won of its profit from one of them — Hana Bank, the commercial bank built around Korea’s former dedicated foreign-exchange institution.
The legal entity — Hana Financial Group Inc., 주식회사 하나금융지주 — was incorporated on 1 December 2005 under Korea’s Financial Holding Companies Act, with its head office at 66 Euljiro, Jung-gu, Seoul. It does almost nothing itself: it owns shares in operating companies, funds them, and manages them. (Source: DART H1 2026 half-year report, rcpNo 20260814003800, Section I.)
The group consolidates 512 entities, of which 103 are classed as material. Most of the rest are securitisation vehicles and private funds that consolidate on technical control grounds, not businesses. The businesses that matter are:
| Subsidiary | What it does | H1 2026 net profit | % of group |
|---|---|---|---|
| Hana Bank | Commercial bank; FX, trade finance, private banking | $1,571M | 88.3% |
| Hana Securities | Brokerage, IB, trading | $202M | 11.4% |
| Hana Card | Credit cards (incl. the “Travelog” FX card) | $93M | 5.2% |
| Hana Capital | Auto and equipment finance, leasing | $77M | 4.3% |
| Hana Life · F&I · Alt. AM · others | Life insurance, NPL investing, alternatives | $46M | 2.6% |
| Hana Insurance | General insurance (motor, fire) | −$53M | −3.0% |
| Holding company + consolidation (derived) | Parent costs, eliminations | −$158M | −8.9% |
Source: DART H1 2026 half-year report (rcpNo 20260814003800), Section II “Business Overview”, which states each subsidiary’s cumulative half-year result. Converted at ₩1,350.36/$1 (FDR, 22 Sep 2026 close) and expressed against group profit attributable to owners of the parent of ₩2,402,868m ($1,779M). Percentages sum to more than 100% because the holding-company and consolidation line is negative. That last line is derived, not disclosed — it is the residual between the subsidiary results the filing states one by one and the consolidated total, so it absorbs parent-company costs, intra-group eliminations and any rounding in the stated figures.
The scale: $528bn of total assets at 30 June 2026, and $320bn of loans at amortised cost and $294bn of deposits on H1 average balances. Hana Bank runs 610 domestic offices. Its overseas count depends on which page of the filing you read — the separate-entity branch table gives Hana Bank 28 overseas offices, while the business-overview narrative in the same document says 114, a wider count that folds in the overseas banking subsidiaries. The group-level figure, and the one worth carrying, is 195 network locations across 27 regions — unusually wide for a Korean bank, and an inheritance from the Korea Exchange Bank merger described below. (All from rcpNo 20260814003800: Section II.1 business overview and Section II.4 “Business Facilities”.)
📊 Where Does Hana’s Revenue Actually Come From?
Two-thirds of Hana’s operating income is the spread between what it pays depositors and what it charges borrowers; almost all of the rest is fees, trading and foreign exchange. If you are used to reading industrial companies, forget revenue and operating margin — for a bank holding company both are meaningless. Hana’s own filings report a “revenue” line that adds together interest income, fee income, financial-instrument gains and FX turnover, and it can swing by tens of percent in a half-year for reasons that have nothing to do with the bank getting better. Read the operating-income mix instead.
| Operating income component | H1 2026 | % of total | FY2025 % |
|---|---|---|---|
| Net interest income | $3,561M | 65.1% | 68.7% |
| Net fees and commissions | $1,233M | 22.5% | 20.4% |
| Gains on FVPL financial instruments | $449M | 8.2% | 7.9% |
| Foreign-exchange trading | $187M | 3.4% | 1.1% |
| Everything else (net) | $39M | 0.7% | 2.0% |
| Total operating income | $5,469M | 100% | 100% |
Source: DART H1 2026 half-year report (rcpNo 20260814003800), consolidated group operating results. Components sum to the total exactly. FX ₩1,350.36/$1. FVPL = fair value through profit or loss.
Quick Take: The FX line looks trivial at 3.4%. It isn’t the point. Hana Bank was built out of Korea Exchange Bank, the country’s dedicated trade-finance institution, and the group still carries $26.9bn of foreign-currency loans and a 195-office network across 27 regions. FX shows up as a small direct trading line and as a large indirect exposure — currency moves swing both the trading result and the reported capital ratio, in opposite directions and different quarters.
🗓️ How Did Hana Get Here? A Short History
Hana began life in 1971 as a short-term finance house rather than a bank, and it reached its present size by absorbing Korea Exchange Bank in 2015.
| Year | What happened |
|---|---|
| 1971 | Founded as Korea Investment Finance (한국투자금융) — a short-term finance house, not a bank. |
| 1991 | Converted into Hana Bank. |
| 2005 | Hana Financial Group Inc. incorporated (1 December) as the holding company. |
| 2013–14 | Korea Exchange Bank‘s affiliates absorbed and rebranded — KEB Capital → Hana F&I (2014), KEB Card → Hana Card (1 Dec 2014). |
| 2015 | 1 September: Korea Exchange Bank and Hana Bank merge. The surviving bank takes KEB’s global network — Germany, Brazil, Canada, Russia, Indonesia, the U.S. |
| 2017 | Head office moves to 66 Euljiro, Seoul. |
| 2020 | The K Non-Life Insurance becomes a subsidiary (May) and is renamed Hana Insurance (10 June) — still loss-making six years on. |
| 2024 | First Value-Up plan filed (29 October): payout to reach 50% in 2027, CET1 held within a 13.0–13.5% band, ROE above 10%, and RWA growth managed at the level of nominal GDP growth. |
| 2026 | Value-Up targets reset upward (24 July): ROE 12%, payout ≥50%, CET1 ≥13% — and both quantitative constraints, the CET1 ceiling and the GDP-linked RWA cap, dropped. |
Sources: DART H1 2026 half-year report (rcpNo 20260814003800), Section I.2 “Corporate History” and the subsidiary name-change schedule; Value-Up filings rcpNo 20260724800373 (2026) and rcpNo 20241029800202 (2024).
🌍 Is Hana a Global Bank or a Korean One?
Hana is a domestic bank with an unusually international balance sheet — third of Korea’s big four by market value, with $26.9bn of foreign-currency loans and a 195-office overseas network, but earnings that are overwhelmingly domestic.
Ranked by market capitalisation on 22 September 2026, the order is KB ($46.15bn), Shinhan ($39.35bn), Hana ($27.29bn), Woori ($19.51bn). Ranked by FY2025 profit attributable to owners, the order is identical: KB $4.32bn, Shinhan $3.68bn, Hana $2.96bn, Woori $2.31bn. Hana is not the leader on any axis a league table measures.
Where it does lead is a narrower thing that Korean investors take for granted and foreign ones rarely see: foreign exchange and trade finance. Korea Exchange Bank was the institution built to finance Korea’s export machine, and when it merged into Hana Bank on 1 September 2015 that book came with it. Hana Bank’s own filing describes a dealing room it calls Korea’s largest, running 24 hours a day, 365 days a year, and a non-face-to-face FX trading platform it calls a domestic first — company-reported claims, made in the filing itself. The group's disclosed foreign-currency loan book — $26.9bn on an H1 2026 average balance — is 5.26% of average deployed assets: small as a share, large as an absolute number for a bank this size, and one reason Hana’s quarterly results move with the won.
Two honest limits on that claim. First, Hana does not disclose a market share for FX or trade finance in its filings, so “leader” here rests on the business’s history and scale, not on a number we can verify. Second — and this is a limit on the size of the prize, not on the claim — Hana does not break out what the FX and trade-finance franchise earns. The only fee figure the filing gives is group-wide: net fees and commissions of $1,233M in H1, 22.5% of operating income, covering card, brokerage, trust, bancassurance and everything else alongside FX. The direct FX trading line is 3.4%. Neither tells you what the franchise itself is worth, and we are not going to impute it.
📈 Is the Business Getting Better or Worse?
Better on the income line and worse on the balance sheet — profit hit a record in the first half of 2026 while the cushion behind the loan book kept shrinking.
| Consolidated group (IFRS) | H1 2026 | H1 2025 | YoY | FY2025 |
|---|---|---|---|---|
| Net interest income | $3,561M | $3,324M | +7.1% | $6,786M |
| — interest income | $8,474M | $8,352M | +1.5% | $16,632M |
| — interest expense | $4,913M | $5,028M | −2.3% | $9,846M |
| Total operating income | $5,469M | — | — | $9,880M |
| Credit-loss provisions | $492M | — | — | $957M |
| Operating profit | $2,405M | — | — | $3,963M |
| Profit attributable to owners | $1,779M | $1,704M | +4.4% | $2,964M |
| Basic EPS (₩, owners’ common) | ₩8,615 | ₩7,972 | +8.1% | ₩13,954 |
Source: DART H1 2026 half-year report (rcpNo 20260814003800), consolidated statement of comprehensive income and summary financial information. All figures consolidated, controlling-interest basis where marked. EPS is basic earnings per common share attributable to owners of the parent, after deducting hybrid-capital distributions — the company’s own line, not a derived figure. Blank cells are where the half-year filing does not publish the prior-period comparative in that table. FX ₩1,350.36/$1.
The margin story is entirely a funding story. Interest income rose 1.5% year on year. Interest expense fell 2.3%. That gap is the whole 7.1% increase in net interest income — Hana is not charging borrowers more, it is paying depositors less. The group’s own reported net interest margin widened 6 basis points to 1.88% in the second quarter (company-reported, from the H1 2026 investor presentation; NIM does not appear in the DART filing). The DART figures that do appear point the same way: deposits are 57.4% of the group’s average funding, the single largest block, and total interest expense fell in absolute terms while the loan book grew.
Two more things the income statement says, both good:
- The profit is clean. Non-operating income was 3.7% of pre-tax profit in H1 2026 and 2.0% in FY2025. There is no large revaluation gain or one-off disposal doing the work — a genuinely unusual property among large Korean listed companies.
- Costs are falling as a share of income. General and administrative expenses were 33.7% of operating income in H1 2026, against 35.1% in FY2025 and 36.4% in FY2024. (Our calculation from the filing. Separately, the company’s H1 2026 investor presentation reports a cost-to-income ratio of 38.76% against 41.20% for FY2025 on its own wider definition — a different base, and one that does not appear in the DART filing at all. Same direction.)
And one that is not: the effective tax rate rose to 27.8% in H1 2026 from 26.1% in FY2025 and 25.4% in FY2024. That is why pre-tax profit grew faster than net profit. The filings do not explain the increase, and we are not going to guess at one.
🔍 What Does Hana’s Own Filing Say About Its Loan-Loss Buffer?
It says the group’s loan-loss reserves fell from a peak of 200.80% of bad loans in the fourth quarter of 2022 to 107.00% at 30 June 2026 — a 93.8-point decline, disclosed as a 46-quarter table inside Hana’s half-year report in Korean, on the financial regulator’s basis, with no commentary attached.
This is the part no English-language source carries, because it is not in the press release, not in the earnings-call script, and not in the summary statements a data terminal scrapes. It sits in the section of the filing that supports Hana’s contingent-capital disclosure, as a plain quarterly series running from the first quarter of 2015 to the second quarter of 2026. Read the whole 46 quarters, not a convenient slice of them — the slice changes the answer, and it cuts both ways. Here is what it shows.
| Group consolidated (FSS basis) | Dec 2023* | Dec 2024 | Dec 2025 | Jun 2026 |
|---|---|---|---|---|
| Total loans (총여신) | — | $303bn | $319bn | $339bn |
| Substandard-and-below loans | — | $1.66bn | $1.88bn | $2.54bn |
| Substandard-and-below ratio | 0.47% | 0.55% | 0.59% | 0.75% |
| Loan-loss reserves | — | $2.32bn | $2.38bn | $2.72bn |
| Coverage ratio | 167.1% | 139.2% | 126.5% | 107.0% |
Source: DART H1 2026 half-year report (rcpNo 20260814003800), Section II.5 “Soundness Status” and Section XI “Trend of Related Indicators”. Prepared on the basis of the business reports Hana submits to Korea’s Financial Supervisory Service. June 2026 figures are marked provisional in the filing. “Total loans” is the filing’s own label, 총여신 — it is the loan base the supervisory ratios are struck on, not a wider credit-exposure measure. *The money rows come from the three-date soundness table, which publishes December 2024 onward only; the December 2023 ratios come from the 46-quarter indicator series in the same filing, which does not publish the underlying amounts. Converted at ₩1,350.36/$1; the underlying disclosure is in won. Arithmetic check: $2.72bn ÷ $2.54bn = 107.0%; $2.54bn ÷ $339bn = 0.75%.
Quick Take — where the 46 quarters cut against us: 107.00% is the lowest cover Hana has reported since the second quarter of 2018, and the 0.75% bad-loan ratio is the highest since the first quarter of 2018. That is eight years, which is the honest version of the alarm. But the same series shows cover as low as 70.20% in 4Q 2015, and below today’s level for every quarter from 1Q 2015 to 2Q 2018 — so 107% is not unprecedented and Hana has operated well beneath it. What is different now is direction: back then the bad-loan ratio was 1.2–1.4% and falling as cover climbed. Today it is 0.75% and rising while cover falls. The level is unremarkable; the pairing is not.
The three rates of change are the story. Over the 18 months from December 2024:
- Total credit exposure grew 11.7%.
- Substandard-and-below loans grew 52.4%.
- Loan-loss reserves grew 17.2%.
Bad loans are compounding four and a half times faster than the book, and provisions are not keeping up. That is the entire mechanism behind the coverage collapse, and it is arithmetic, not interpretation.
It is sharper at the bank than at the group. Hana Bank’s own coverage — on a separate-entity basis, using the reserve total against substandard-and-below loans, as the filing defines it — went 165.3% (Dec 2024) → 136.3% (Dec 2025) → 100.35% (Jun 2026), while its substandard-and-below ratio went 0.29% → 0.35% → 0.48%. At Hana Capital, the consumer and equipment finance arm, coverage fell from 114.7% to 87.2% in six months while the bad-loan ratio went 1.62% → 2.01%. (Same source, subsidiary soundness table.)
Is Hana alone in this, or is it the whole sector?
All four of Korea's big financial groups filed the same supervisory indicators on the same day — though not, it turns out, in the same form — and Hana comes last on both capital and cover. This is the check that separates a company story from a sector story, and it takes about twenty minutes if you can read the filings.
One thing to get straight before the table, because it is where a careless comparison goes wrong. Hana, Shinhan and Woori each publish a consolidated soundness table that prints the components — reserve balance, substandard-and-below balance, and the ratio between them — so their cover can be recomputed from the filing. KB does not. KB’s coverage appears only as a row in its long quarterly indicator series, under a differently worded label (“loan-loss reserve ratio against substandard-and-below loans”), and KB’s filing never prints the reserve balance anywhere — so KB’s 112.16% has to be taken as published rather than rebuilt. KB’s bad-loan ratio is also simply higher: 1.01% against Hana’s 0.75%, on the same 총여신 base. So KB covers a considerably bigger problem book at a similar ratio, and its coverage number carries one less layer of verification than the other three.
| Group, 30 Jun 2026 | CET1 ratio | Substandard-and-below | Coverage ratio |
|---|---|---|---|
| Shinhan Financial (055550) | 13.43% | 0.79% | 117.0% |
| Woori Financial (316140) | 13.74% | 0.73% | 112.9% |
| KB Financial (105560) | 13.74% | 1.01% | 112.2% |
| Hana Financial (086790) | 13.27% | 0.75% | 107.0% |
Sources: each group's own H1 2026 half-year report, all filed 14 August 2026 and all on the Financial Supervisory Service's business-report basis — Hana rcpNo 20260814003800, KB rcpNo 20260814004200, Shinhan rcpNo 20260814003306, Woori rcpNo 20260814003410. Each figure was read directly from the filing named beside it. Shinhan's printed coverage value is 116.97%, KB's 112.16%, Woori's 112.9%, Hana's 107.00%. Two basis notes. (1) Every CET1 figure here is the ratio as filed with DART; each group’s own investor presentation states a slightly different estimate — Hana’s says 13.21% against the filed 13.27%, Woori’s 13.71% against the filed 13.74% — and mixing the two sources across companies manufactures differences of a few basis points that do not exist. We use the filed number for all four. (2) “Provisional” is not uniform: Hana, Woori and KB each mark their June 2026 figures provisional, and Shinhan’s soundness table carries no such note. KB’s coverage row comes from its indicator series rather than a soundness table, for the reason given above. We take each of the other three apart the same way, from its own filings: KB Financial Group (105560), Shinhan Financial Group (055550) and Woori Financial Group (316140).
So it is both — but the four are not moving together. Measured over the same eighteen months from December 2024 — each figure read from that company's own filing, and KB's from its indicator series because KB files no soundness table for cover — Woori's cover fell 40.1 points (153.0% → 112.9%), Hana's fell 32.2 points (139.2% → 107.0%) and Shinhan's fell 15.5 points (132.5% → 117.0%), while KB's was essentially flat (113.1% → 112.2%). Three of four are drawing down a buffer; one is not. Woori fell furthest in points, but from the highest starting level. Hana is the one that ends lowest, and it is also the one with the thinnest common-equity capital. The gap is real money: to sit where Shinhan sits at 117.0%, Hana would need roughly $253M more provisions than it carries today. Being last on both measures at once is the Hana-specific part of this.
⚠️ What restoring the buffer would cost
This is a cost that can be sized, which is what makes it a different kind of risk from a mark-to-market loss. Against June 2026’s $2.54bn of substandard-and-below loans:
- Returning coverage to December 2025’s 126.5% requires roughly $496M of extra provisions — about 16.7% of FY2025 profit attributable to owners.
- Returning it to December 2024’s 139.2% requires roughly $817M — about 27.5%.
Our calculation, from the filed figures above. It assumes the bad-loan balance stays where it is. That is the optimistic assumption in a series that has risen from 0.39% to 0.75% since the first quarter of 2023 — though not in a straight line: it dipped in the fourth quarter of 2025 before jumping again.
🧾 Why Are There Two Different Coverage Ratios for the Same Bank?
Because the regulator and the company count bad loans differently — Hana’s DART filing shows 107.0% coverage on the supervisory definition, while its own investor presentation shows 86.4% on a narrower non-performing-loan definition, and both are correct.
The supervisory measure uses substandard-and-below loans (고정이하여신), the asset-classification category Korean regulators require. The company’s investor deck uses an NPL definition that captures a different slice — which is why the same June 2026 balance sheet produces a 0.75% bad-loan ratio in the DART filing and a 0.93% ratio in the presentation, and a coverage ratio 20 points apart.
Most foreign coverage of Korean banks quotes whichever number reaches it first and never says which basis it is. If you are comparing Hana with a European or U.S. bank, or with KB and Shinhan, the basis has to match or the comparison is noise. The direction, mercifully, does not depend on the definition: coverage is sharply lower on both measures than it was in 2023, and the company’s own number is the lower of the two. It has not fallen every single quarter — the supervisory series rose in the fourth quarter of 2025, from 118.23% to 126.54%, before dropping to 116.65% and then 107.00% — and a quarter of improvement is exactly what a bull case here would need to see repeated.
💧 Where Did Korea’s Banks Find $18bn of New Dividend Capacity?
In the first half of 2026, Hana, KB and Shinhan each converted a large slab of capital surplus into distributable retained earnings — $5.5bn, $5.6bn and $7.3bn, $18.3bn between them — legally expanding how much they are allowed to pay out. Woori had already done it a year earlier, at its March 2025 meeting, creating ₩3.0tn ($2.22bn) of distributable income — so all four have now used the same provision, and Woori used it first — a year before the other three. (We checked the 2025 meetings too, not just 2026: that is the only reason Woori is in this sentence rather than excluded from it. Woori’s 26 March 2025 AGM-result filing, rcpNo 20250326802725, records the reduction as agenda item 3 and states the distributable income it created.)
Under Article 461-2 of Korea’s Commercial Act, a company can reduce its capital reserve and transfer the amount into retained earnings. Nothing about the business changes. Total equity does not move. What moves is the legal ceiling on distributions: in Korea, dividends and buy-and-cancel programmes must come out of distributable profit, and capital surplus does not count. Move it, and it does.
| Consolidated balance sheet | Capital surplus Dec 2025 |
Capital surplus Jun 2026 |
Reduction |
|---|---|---|---|
| Shinhan Financial | $8.96bn | $1.65bn | −$7.31bn |
| KB Financial | $12.32bn | $6.76bn | −$5.56bn |
| Hana Financial | $7.83bn | $2.35bn | −$5.48bn |
| Woori Financial | $0.69bn | $0.69bn | none |
Source: DART consolidated balance sheets from each company’s H1 2026 half-year report (API endpoint fnlttSinglAcntAll, report code 11012, consolidated). Hana’s own figures: capital surplus ₩10,576,317m → ₩3,175,792m; retained earnings ₩29,690,875m → ₩38,432,971m. FX ₩1,350.36/$1 throughout.
Hana’s move was approved at its annual general meeting on 24 March 2026 as agenda item 2, “Reduction of Capital Reserve”, and carried with 99.98% of votes cast. Four months later, on 24 July, the board raised the group’s Value-Up targets. The order matters: the legal constraint was removed first, the promise was made second.
What we would have got wrong, reading Hana alone, is the significance. Our earlier internal research treated Hana's $5.5bn reduction as a company-specific discovery. Pulling the same balance-sheet line for all four holding companies shows it was a sector move — three of the four did it within the same half-year, and Shinhan’s was the largest. That reframes it: this is not one company getting clever, it is Korea’s banking sector collectively rebuilding its distribution headroom ahead of the country’s new dividend tax regime and the next phase of the Value-Up programme. If you hold any Korean bank, this happened to your company too.
✂️ Has Hana Actually Cancelled the Shares It Bought Back?
Yes — 29,272,152 shares, or 9.75% of every share the company has ever issued, have been permanently retired, and the three numbers reconcile to the exact share count KRX lists today.
This distinction is where English-language coverage of Korean buybacks falls apart. A Korean company files a treasury-share acquisition decision when it starts buying, and a separate share cancellation decision when it destroys what it bought. Headlines conflate the two. Samsung Electronics' large 2026 programme, for example, is disclosed as an employee-compensation buyback — the share count does not fall. Hana’s are buy-and-cancel, and you can prove it without trusting anyone:
| Share ledger | Shares | Source |
|---|---|---|
| Total ever issued since inception | 300,242,062 | H1 2026 filing, share-total schedule (line Ⅱ) |
| Cancelled out of distributable profit, to 30 Jun 2026 | −25,874,314 | Same schedule, “profit cancellation” (line Ⅲ.2) |
| = Shares issued at 30 Jun 2026 | 274,367,748 | Same schedule (line Ⅳ) |
| Cancelled 28 Aug 2026 (two tranches) | −3,397,838 | rcpNo 20260826800242 / …245 |
| = Shares listed on KRX, 22 Sep 2026 | 270,969,910 | KRX daily trading data |
| Less: the one treasury block that survived the cancellation | −4,340,000 | Treasury schedule; 4,340,000 at 30 Jun and unchanged by the cancellation |
| = Outstanding, excluding that block | 266,629,910 | Matches the dividend-eligible count in rcpNo 20260724800419 |
Sources: DART H1 2026 half-year report (rcpNo 20260814003800), share-total schedule and treasury schedule; cancellation filings of 26 August 2026; KRX Open API settled daily trading data for 22 September 2026. Total treasury was 7,260,497 shares — 2.65% of the 274,367,748 then issued — at 30 June 2026, not 4,340,000; the difference is explained in the paragraph below. The last line is a floor, not a count: the third 2026 buyback tranche was still buying in the market on 22 September, and Hana does not disclose that holding daily.
How the treasury balance gets from 7,260,497 to 4,340,000 is worth following, because it is the check that proves the cancellation was real. At 30 June the filing shows 7,260,497 treasury shares in two blocks: 2,920,497 bought directly in the market under the buy-and-cancel programmes, and 4,340,000 held since 2019. The same filing says the second 2026 tranche was only 70.7% executed at the half-year date and completed on 10 July. Add the 477,341 shares bought in those ten days and treasury reaches 7,737,838; subtract the 3,397,838 cancelled on 28 August and you land on 4,340,000 exactly. Every share the two programmes bought was destroyed; the 2019 block was not touched.
The cancellations are genuinely executed rather than announced — but be careful which money figure you quote, because Hana’s filings print three different ones for the same two tranches. We use one basis throughout: the acquisition cost of the cancelled shares, the amount each cancellation filing gives as its 소각예정금액 and defines in its own note as “the acquisition cost of the shares to be cancelled.” On that basis the 28 August event retired 1,750,497 shares bought for ₩199,800,081,800 under the 30 January board resolution, and 1,647,341 shares bought for ₩199,800,139,700 under the 24 April resolution. Each resolution had authorised ₩200.0bn, so execution landed within 0.1% of budget both times. The filings also spell out why the share counts moved: the budget is fixed in won, so “the number of shares changed to 1,647,341 in line with the share-price movement during the acquisition period.” A lower share price buys and destroys more shares. (Sources: rcpNo 20260826800242 for the 1,750,497-share tranche and rcpNo 20260826800245 for the 1,647,341-share tranche.)
Add the two and the August cancellation cost Hana ₩399,600,221,500 — $295.9M. (Our addition of the two filed amounts. Neither filing prints a total, and no filing anywhere prints this number: it is ours.)
The other two bases, for completeness. The authorised budget was ₩200.0bn per tranche. And the half-year report’s treasury-execution table shows ₩199,999,881,780 and ₩199,999,939,700 for the identical purchases, because that table is struck including all brokerage fees. The spread across the three bases is small — a few hundred million won on ₩400bn — but they are three different numbers that all round to “about $148M a tranche”, and a reader checking us against a wire report needs to know which one we picked. (Source: rcpNo 20260814003800, treasury direct-acquisition execution table.)
Now the part that does not flatter the story. Two things are still open:
- The third 2026 tranche is not done. The 24 July board resolved a further $185M, estimated at 1,915,708 shares based on the prior day’s ₩130,500 close. Its buying window runs 27 July to 22 October 2026 and the cancellation date field in the filing reads “—”. The company states it intends to cancel the entire amount once buying completes. As of our 22 September data cutoff it is a programme in progress, not a completed return. (Source: rcpNo 20260724800414.)
- 4,340,000 treasury shares have never been cancelled — and the filing puts a 2027 deadline on them. They are 1.60% of the shares listed today, bought and parked. The treasury-holding schedule dates their acquisition to 2019, gives their purpose as “share-price stabilisation and enhancing corporate value” — not the buy-and-cancel purpose it gives the other two blocks — and prints a cancellation deadline of 2027. The corporate-history section shows the same 4,340,000 standing as the residue of the April 2022 cancellation, verbatim: “22 April 2022 — Hana Financial Group treasury-share cancellation resolved (4,338,586 shares cancelled, 4,340,000 treasury shares remaining).” It has not moved since. Two schedules inside the one filing classify the block differently — the acquisition-method table files it under trust-contract holdings, the holding schedule under direct purchases out of distributable profit — so we will not tell you which it is.
The deadline comes from Korea’s amended Commercial Act, effective 6 March 2026: treasury stock must in principle be cancelled within one year of acquisition, shares already held when the law took effect get one year and six months, and the only way out is a shareholder-approved holding-and-disposal plan. The amendment also tightened the rules on trust arrangements, so a trust classification is no shelter. In Hana’s filing the shareholder-approval columns are blank — no plan has been approved — and the company’s own long-term treasury plan reads: “the 4,340,000 shares retained under the short-term plan will in future be cancelled by board resolution, or held or disposed of with the approval of the general meeting.” The 2027 annual meeting is where it surfaces. (Sources: rcpNo 20260814003800, treasury-holding schedule, corporate-history schedule and long-term treasury plan; Financial Services Commission press release of 30 March 2026.)
Across 2026 the board has resolved ₩650bn ($481M) of buy-and-cancel in three tranches — ₩200bn in January, ₩200bn in April, ₩250bn in July. That is authorised budget, not money spent: ₩399.6bn ($295.9M) of it has been bought and cancelled, and the July tranche was still buying at our data cutoff. For FY2025, dividends of ₩1,117.8bn ($828M) plus ₩750bn ($555M) of buyback resolutions came to roughly 46.7% of profit attributable to owners — against the company’s stated target of 50%-plus. (Our calculation, attributing buybacks to the year of board resolution. The company’s own payout figures are dividends-only, and it prints two of them for FY2025: 28.00% as the consolidated cash-payout ratio in the annual report’s dividend schedule, and 27.9% in the July 2026 Value-Up filing’s high-dividend-company section.)
💰 What Do You Actually Pay for Hana Today?
₩136,000 a share (~$100.71) as of 22 September 2026 — 9.8 times last year’s earnings, 0.79 times book value, and a 3.0% dividend yield.
| Hana Financial Group (086790) | Value | As of |
|---|---|---|
| Share price | $100.71 (₩136,000) | 22 Sep 2026 close |
| Market capitalisation | $27.29bn | 22 Sep 2026 |
| P/E on FY2025 EPS (₩13,954) | 9.75× | FY2025 / 22 Sep price |
| P/E on trailing-12-month EPS (₩14,597) | 9.32× | To Jun 2026 / 22 Sep price |
| P/B on equity attributable to owners | 0.79× | Equity at 30 Jun 2026 |
| P/B excluding hybrid capital | 0.87× | Equity at 30 Jun 2026 |
| Dividend yield (FY2025 DPS ₩4,105) | 3.02% | FY2025 / 22 Sep price |
| Year to date / 52-week closing high | +44.5% / ₩140,800 | From ₩94,100, 30 Dec 2025 |
Sources: KRX Open API settled daily trading data (close, listed shares 270,969,910, market cap ₩36,851,907,760,000 — the three reconcile exactly); DART FY2025 annual report as amended (rcpNo 20260814004019, [기재정정]사업보고서 (2025.12)) for EPS ₩13,954 and DPS ₩4,105; DART H1 2026 half-year report for equity attributable to owners of ₩46,876,523m and hybrid capital of ₩4,399,244m. FX ₩1,350.36/$1 (30 Dec 2025 close ₩94,100 from KRX). These are point-in-time figures and go stale — check a live quote before acting on any of them.
Quick Take — the hybrid-capital trap: Screening sites routinely divide market cap by total equity and report Hana at a much lower P/B than reality. Hana's equity attributable to owners includes $3.26bn of perpetual hybrid securities — accounted for as equity under IFRS, but the coupon is paid before common shareholders see anything. Hana deducted $64M of hybrid distributions before striking its H1 EPS; do the same before striking book value. Excluding the hybrid, Hana’s P/B is 0.87×, not 0.79×. Note also that KRX market cap counts all 270,969,910 listed shares, treasury included — and at least 4,340,000 of them are in treasury, plus whatever the in-flight third buyback tranche has bought since 30 June. Net of the 4,340,000 alone, the ratios are about 1.6% lower again.
How does that compare with the other three?
Hana is the third-largest of the four and the third-cheapest on price-to-book, but the cheapest of the three majors on earnings and the highest-yielding of them. Every figure below is computed the same way for all four companies: KRX settled close of 22 September 2026, company-disclosed FY2025 EPS on a controlling-interest basis from each issuer’s own DART filing, and equity attributable to owners of the parent at 30 June 2026.
| Korea’s big four | Market cap | P/E | P/B | Yield | Payout |
|---|---|---|---|---|---|
| KB Financial (105560 · NYSE: KB) | $46.15bn | 11.40× | 1.02× | 2.49% | 27.00% |
| Shinhan Financial (055550 · NYSE: SHG) | $39.35bn | 11.54× | 0.88× | 2.29% | 25.06% |
| Hana Financial (086790 · no ADR) | $27.29bn | 9.75× | 0.79× | 3.02% | 28.00% |
| Woori Financial (316140 · NYSE: WF) | $19.51bn | 8.82× | 0.68× | 3.80% | 31.96% |
Sources: KRX Open API settled closes and listed-share counts, 22 Sep 2026; DART alotMatter dividend disclosures for FY2025 (EPS on a consolidated, controlling-interest basis; payout is the consolidated cash-payout ratio each company itself discloses in that schedule — dividends only, no buybacks — taken from the same line for all four so the column is comparable, which is why Hana reads 28.00% here and 27.9% in the Value-Up filing quoted later); DART consolidated balance sheets at 30 Jun 2026 for equity attributable to owners. Excluding hybrid capital the P/B ranking is unchanged: KB 1.10×, Shinhan 0.95×, Hana 0.87×, Woori 0.75×. The ADR symbols are each issuer’s NYSE line; “no ADR” for Hana is an SEC EDGAR check, sourced in the ticker section below.
The ordering is stable however you cut it, and it is not an accident. KB is the most expensive and the most diversified by business mix; Woori is the cheapest and the most bank-dependent; Hana sits third. Hana’s own numbers say why: 88.3% of first-half subsidiary profit came from Hana Bank. The company reports non-bank businesses at 18.8% of consolidated net income for H1 2026 — a real improvement, and a figure that excludes the negative holding-company and consolidation line. Hana is also unusually candid about the discount. Its first Value-Up filing names three causes of its own undervaluation in the company’s own words: “① a shareholder-return ratio low relative to global financial stocks, ② a conservative capital-management policy, and ③ an ROE below the cost of equity (COE).” A bank saying in a regulatory filing that it does not earn its cost of capital is not a common sentence. (Source: rcpNo 20241029800202, our translation. Note that Value-Up filings carry a standing caveat that they contain forward-looking information which may differ from actual results — these are the company’s targets, not forecasts, and not ours.) Whether that mix shift sticks is the single most important valuation question here, and one good half-year does not settle it: Hana Securities’ contribution is a function of a strong Korean equity market, and Korean equity markets do not stay strong on request.
🏷️ Which Hana Ticker Are You Buying — and Is There an ADR?
There is exactly one Hana Financial Group line — KRX ticker 086790 — and unlike KB, Shinhan and Woori, it has no U.S.-listed ADR, so a foreign investor has to buy it in Seoul in won.
That is a genuine structural difference and worth stating plainly, because it explains a lot of the coverage gap. Our list of exchange-listed Korean ADRs names ten companies, including three of the four bank holding groups. Hana is the one that is absent, and we checked that the hard way rather than by looking at the list: a search of the SEC’s EDGAR registrant database returns no Form F-6 registration, and no registrant of any kind, for Hana Financial Group or KEB Hana — while the same search returns F-6 registrations for Woori, KB and Shinhan, and even for unrelated issuers whose names begin “Hana”. Every ADR programme, sponsored or unsponsored, needs an F-6. There isn’t one. (Source: SEC EDGAR company search, checked 27 Sep 2026.) No ADR means no U.S. filing calendar, no dollar-denominated line for a U.S. screen to pick up, and far less incentive for anyone to translate the filings. A company with a $27bn market value drops out of the English-language information flow almost entirely.
Three ways to get it wrong:
- Hana Financial Group (086790) is the listed holding company. Hana Bank, Hana Securities, Hana Card and the rest are wholly or majority owned and not separately listed. Only one entity in the entire 512-company consolidation is listed, and this is it.
- “KEB Hana” is the same company. Korea Exchange Bank ceased to exist as a separate entity on 1 September 2015; the “KEB Hana” branding that survives on some overseas units is a legacy name, not a different security.
- There are no preferred shares. Hana’s share-total schedule lists nil preference stock — the common line is the whole equity. That is not true of every Korean large-cap, and checking it is a habit worth keeping.
If you are buying the local line, the practical questions are broker access, FX and withholding — covered in our guides to buying Korean stocks as a foreign investor and to Korean dividend withholding tax. The withholding point matters disproportionately for a stock bought for its yield: Hana’s 3.02% gross yield is roughly 2.52% net for a U.S. resident claiming treaty relief, and about 2.36% for someone who does not claim it.
🌏 Is Foreign Money Buying or Selling Hana?
Selling — consistently, across every window we measured, and across three of Korea’s four bank holding companies, while domestic institutions bought the other side and the share price rose 18.5%.
A single window invents narratives, so here are three, side by side, ending on the same settled session.
| Investor flows | Foreign net buy, 5 sessions |
Foreign net buy, 20 sessions |
Foreign net buy, 60 sessions |
Institutional net buy, 60 sessions |
Price, 60 sessions |
|---|---|---|---|---|---|
| Hana Financial (086790) | −$44.7M | −$79.3M | −$169.1M | +$311.2M | +18.5% |
| KB Financial (105560) | −$72.7M | −$150.5M | −$484.2M | +$669.5M | +14.3% |
| Shinhan Financial (055550) | −$32.6M | −$177.3M | −$249.5M | +$487.6M | +17.4% |
| Woori Financial (316140) | −$25.8M | +$365.8M | +$370.5M | +$231.3M | +22.9% |
Source: our own investor-flow database, built from Korea Investment & Securities Open API daily data across 2,555 KRX-listed stocks. Windows are trading sessions ending 22 September 2026 (5 sessions = 16–22 Sep; 20 = 26 Aug–22 Sep; 60 = 29 Jun–22 Sep). Flows arrive as share counts; the dollar figures multiply each day’s net shares by that day’s close and sum — an approximation, not execution prices — then convert at ₩1,350.36/$1. Hana’s underlying share counts: −446,309 / −795,859 / −1,780,460.
Three readings, in order of how confident we are:
- This is not a Hana signal. Foreigners sold Hana, KB and Shinhan in all three windows. When three of four names in a sector move together, you are looking at a sector or index flow, not a verdict on one balance sheet. Woori is the exception in the 20- and 60-session windows; we have not established why, and it is a Woori question rather than a Hana one.
- The size is small. Hana’s 60-session foreign net sale of 1,780,460 shares is 0.67% of shares outstanding. Over 20 sessions it is 0.30%. These are not the numbers of an exit.
- Domestic institutions took the other side and the stock went up. Institutions bought 3,225,969 Hana shares over 60 sessions while the price rose 18.5%. Whatever the foreign seller was doing, it was not setting the price.
For the weekly version of this analysis across the whole market, see our Foreign Flow Watch series.
🏛️ Who Controls Hana, and What Do Minority Shareholders Get?
Nobody controls Hana — its largest shareholder is Korea’s National Pension Service at 8.90% of shares issued, its second and third are BlackRock and Capital Group, and 73.44% of the shares that carry votes belong to 161,982 small holders.
| Shareholder | Shares | Stake, as filed | Denominator · as of |
|---|---|---|---|
| National Pension Service (largest holder) | 24,408,932 | 8.90% | 274,367,748 issued · register, 30 Jun 2026 |
| BlackRock Fund Advisors | 19,800,826 | 7.22% | 274,367,748 issued · large-holding report, 20 Feb 2026 |
| Capital Research and Management | 15,436,551 | 5.63% | 274,367,748 issued · large-holding report, 31 Mar 2026 |
| Employee stock ownership association | 4,263,072 | 1.55% | 274,367,748 issued · 30 Jun 2026 |
| Minority shareholders (161,982 holders) | 196,173,311 | 73.44% | 267,107,251 voting shares · 30 Jun 2026 |
Source: DART H1 2026 half-year report (rcpNo 20260814003800), Section VII “Shareholders”. Read the last column: the filing itself uses two different denominators and says so. The named holders are struck against the 274,367,748 shares issued at 30 June 2026; the minority line is struck against 267,107,251, which the filing footnotes as “the total number of issued shares carrying voting rights” — issued shares less the 7,260,497 in treasury. Put every line on that voting base instead and NPS is 9.14%, BlackRock 7.41% and Capital Group 5.78%. The two foreign stakes are also dated differently from the header: they are the as-of dates of each manager’s own 5% large-holding report, not 30 June positions, and neither has been refreshed since. NPS raised its stake from 8.66% at end-2025.
For an investor who has read about Korea before reading about Hana, this is the section that should recalibrate expectations. The standard Korea Discount narrative is about chaebol control: a founding family with a modest economic stake but decisive voting power, an incentive to move value between affiliates, and a history of treating minority holders as an afterthought. None of that machinery exists here. Hana has no controlling family, no circular shareholding, no affiliate propping up a parent. Two of its three largest holders are global index and active managers.
That does not make the governance question go away; it changes it. A company with dispersed ownership has the opposite problem — management can end up controlling the board rather than the board controlling management — and the right things to monitor are board independence, CEO succession and the quality of the evaluation process, not related-party dealings. Hana’s audit committee is composed entirely of outside directors, and the 2026 annual meeting saw outside-director appointments pass with support in the 77–84% range of total shares issued, with a handful of candidates drawing measurable opposition. That is a governance record worth tracking, not one worth dismissing.
The shareholder-return promise, and what it actually commits to
Hana’s 2026 Value-Up plan is unusually specific, and the half-year report restates it in the filing itself rather than leaving it in a slide deck. The targets are ROE of 12%, a shareholder-return ratio of 50% or more, and a CET1 ratio of 13% or more — and the return ratio is defined as a formula, not a discretion:
Shareholder return ratio = 1 − (RWA growth rate ÷ ROE)
“Capital in excess of a 13% common equity tier 1 ratio may be used for shareholder returns under the return framework based on ROE and RWA growth.” — DART H1 2026 half-year report, Section III.6, our translation.
Read the formula both ways. It rises when ROE improves or risk-weighted asset growth slows. It falls when RWA grows fast — and Hana’s RWA grew 6.05% in the first half of 2026 alone, an annualised 12.5%. The 2024 plan had committed to managing RWA growth “at the level of nominal GDP growth”; the 2026 plan replaced that measurable benchmark with a single line of implementation: “maintaining an unwavering enterprise-wide RWA management stance.” The quantitative constraint was removed in the same filing that raised the payout target — and the half-year that followed grew RWA far faster than any plausible nominal GDP growth rate for Korea. (Sources: rcpNo 20241029800202 and rcpNo 20260724800373.)
Capital and target, side by side, because one without the other is not information:
| Group capital | Dec 2024 | Dec 2025 | Jun 2026 | Target |
|---|---|---|---|---|
| CET1 ratio | 13.22% | 13.38% | 13.27% | ≥13.0% |
| Total capital ratio | 15.59% | 15.61% | 15.33% | — |
| Risk-weighted assets | $207bn | $214bn | $227bn | — |
| ROE — our calculation, not a filed ratio | 9.11%* | 9.17%* | 10.51%* | 12% |
Sources: the CET1, total-capital and RWA rows are from the DART H1 2026 half-year report (rcpNo 20260814003800), Section II.5 “Capital Adequacy” and the Section XI indicator trends; the target column is from Value-Up filing rcpNo 20260724800373. June 2026 capital figures are marked provisional. CET1 is the filed ratio and reconciles to CET1 capital ÷ RWA exactly; the company’s H1 investor presentation states 13.21% on its own estimate — we use the filed number. *The ROE row is ours, and it has to be: unlike KB’s and Woori’s, Hana’s half-year report contains no profitability-ratio table and never prints an ROE, an ROA or a net interest margin. We compute it as profit attributable to owners of the parent divided by the simple average of opening and closing equity attributable to owners — ₩3,738,849m ÷ avg(₩39,343,318m, ₩42,701,020m) for FY2024, ₩4,002,882m ÷ avg(₩42,701,020m, ₩44,579,957m) for FY2025, and the H1 2026 result of ₩2,402,868m doubled over avg(₩44,579,957m, ₩46,876,523m). Every input is a filed balance-sheet or income-statement line. Annualising a half-year is not a forecast and not a like-for-like comparison with the full years beside it; the company’s own investor presentation reports 10.62% for the half. On the filing’s numbers the buffer above the 13% floor is 0.27 percentage points, or about $613M of CET1 capital — roughly three more buyback tranches the size of the current one.
⚠️ The Bear Case
⚠️ What would make this thesis wrong
- The provisioning catches up. Bad loans grew 52% in 18 months against 17% reserve growth. If Hana rebuilds coverage to December 2025’s level it costs roughly $496M, or 16.7% of last year’s profit; to 2024’s level, $817M or 27.5%. Neither is fatal. Both would take a year of earnings growth off the table, and the company describes its own provisioning as “at a normal level” — a reading we do not share.
- Some of the improvement is disposal, not recovery — and the company said so before it happened. The H1 filing attributes Hana Capital’s ratios to “active write-offs and sales of non-performing assets”. Three months earlier, in its first-quarter report, Hana wrote of the credit-card sector that “delinquency rates stabilised downward in numerical terms on the back of write-offs and sales of bad debt, but this was attributable to a temporary indicator-management effect, and the substantive soundness burden remained high,” and warned that a rebound was possible once “the previous quarter’s large-scale bad-debt disposals dilute.” That is Hana’s read of the industry rather than of its own book — but in the quarter that followed, the group’s own substandard-and-below ratio went 0.62% to 0.75% and coverage 116.65% to 107.0%. (Sources: H1 2026 report rcpNo 20260814003800; Q1 2026 quarterly report rcpNo 20260515002550, industry-outlook section, our translation.)
- Capital headroom is the thinnest of the big four. CET1 of 13.27% against a 13.0% floor is 0.27 percentage points, and 47 basis points below KB and Woori. RWA grew at a 12.5% annualised pace in H1. The return formula is explicitly a function of RWA growth — if the balance sheet keeps expanding at that rate, the 50% payout target does the arithmetic against itself.
- The non-bank improvement may be cyclical. Hana Securities contributed $202M in H1 2026, which the filing attributes to buoyant domestic equity turnover, expanded margin-lending balances and IB deal closings — and to an S&T result that fell on unexpected market volatility. Hana Insurance lost $53M in the same half — more than its entire FY2025 loss. The bank is 88.3% of subsidiary profit. Call the diversification a trend after two more half-years, not one.
- Earnings growth is the slowest of the four. Profit attributable to owners grew 4.4% in H1 2026. KB and Shinhan grew faster. A 9.8× multiple against an 11.4× peer is a discount; it is not automatically a mispricing, and the market may simply be pricing the growth gap and the single-business concentration correctly.
- Everything above is a snapshot. Prices, flows and the in-flight buyback move daily; the provisional June 2026 capital and soundness figures can be restated; and the $185M buyback tranche running to 22 October will change the share count after this article's data cutoff.
📚 Lingo Check
| Term | What it means |
|---|---|
| Substandard-and-below loans 고정이하여신 |
Korea’s regulatory bad-loan category — the bottom three of five asset-classification grades. It is the denominator in the supervisory coverage ratio and is not the same as the “NPL” figure a company uses in its own investor deck. |
| Loan-loss coverage ratio 대손충당금적립률 |
Loan-loss reserves divided by bad loans. Above 100% means the bank has already set aside more than the face value of its recognised problem loans. Falling coverage flatters current profit and borrows from future profit. |
| Loan-loss reserve vs. regulatory reserve 대손충당금 / 대손준비금 |
Two different things that translate almost identically. The first is a provision charged against profit; the second is an appropriation of equity Korean regulators require on top. Only the first affects reported earnings. |
| CET1 ratio 보통주자본비율 |
Common equity tier 1 capital divided by risk-weighted assets — the core regulatory solvency measure. Korean banks now tie shareholder returns to the surplus above a self-declared CET1 floor, which makes the floor an investor-relevant number, not just a supervisory one. |
| Risk-weighted assets (RWA) 위험가중자산 |
Assets scaled by riskiness. It is the denominator of every capital ratio, so growing it consumes capital that could otherwise be returned — which is why Hana’s payout formula subtracts RWA growth. |
| Hybrid tier 1 / perpetual capital securities 신종자본증권 |
Perpetual instruments booked as equity under IFRS but paying a coupon that ranks ahead of common dividends. Hana holds $3.26bn of them. Include it in book value and you overstate what common shareholders own; Hana deducts its distributions before striking EPS, and so should you before striking P/B. |
| Capital reserve reduction 자본준비금 감액 |
Transferring paid-in capital surplus into retained earnings under Commercial Act Art. 461-2, with shareholder approval. Total equity is unchanged; the legal ceiling on dividends and buy-and-cancel rises by the transferred amount. |
| Cost-to-income ratio (CIR) 판관비율 |
Operating expenses divided by operating income — a bank’s efficiency measure. Definitions differ by issuer, so a CIR is only comparable when the base is stated. |
Definitions drawn from our editorial glossary; existing entries for treasury-share cancellation, distributable profit, buyback trust contract, high-dividend company (고배당기업) and Korea Discount apply here unchanged.
🎯 Why It Matters for K-Export Stars
This site exists because a meaningful amount of what a foreign investor needs to know about a Korean company is written down, filed publicly, and never translated. Hana is close to a pure test of that proposition. It is a $27bn company in the KOSPI top 20, with no ADR and very little English-language analysis of its actual filings.
Three things in this piece came out of reading the Korean filings rather than the press releases, and none of them appeared in the English coverage of Hana’s record half-year:
- A 46-quarter regulatory table showing loan-loss cover falling 93.8 points from its 2022 peak, buried in a section about contingent capital — and showing, in the same rows, that today’s 107% is not a record low.
- Two different coverage ratios for the same balance sheet — 107.0% and 86.4% — that are both correct and are never reconciled in English.
- A $5.5bn capital-reserve reduction that is not a Hana story at all, but a sector story — visible only by pulling the same balance-sheet line for all four holding companies, and only complete once you look at 2025 as well as 2026, because Woori did it a year before the rest (rcpNo 20250326802725).
- And the reverse: a loan-loss cover ratio that is Hana-specific once you put the four side by side — three of the four are drawing their buffer down, KB is not, and Hana ends lowest.
The last one is the most useful, and it is the one we got wrong the first time. Reading a single company’s filing tells you what happened to that company. Reading the same line across its peers tells you whether it means anything. That is the difference between a fact and an insight, and it is why every company piece on this site now carries a peer table computed the same way.
Conclusion
Hana Financial Group is the cheapest of Korea’s three largest banks on earnings and the highest-yielding of them, and it has permanently destroyed nearly a tenth of every share it ever issued — verifiably, with the ledger reconciling to the exact count KRX lists today. That is an unusually clean shareholder-return record by any market’s standards.
It is also a bank whose loan-loss cushion has fallen 93.8 points since its 2022 peak, with one quarter of respite in late 2025, whose capital buffer above its own declared floor is 0.27 percentage points, and whose risk-weighted assets grew at a 12.5% annualised rate in a half-year in which management promised “unwavering” RWA discipline. The discount and the concern are not separate observations. Ninety percent of the profit comes from one bank, and the one bank’s coverage ratio is at 100.35%.
Neither fact settles the question — that is the reader’s job, with a live quote and a view on Korean credit. What we can say is that both facts are in the filings, in Korean, and that the second one has not been translated. If you want the market-wide version of the flow data above, read our Foreign Flow Watch; for the policy backdrop behind every payout number here, start with our guide to Korea’s Value-Up programme.
Disclosure of interest. The author holds a position in Hana Financial Group (086790) — a single share, held as a research position, worth approximately $101 at the price used throughout this article. The author holds no position in KB Financial Group (105560), Shinhan Financial Group (055550) or Woori Financial Group (316140), the three peer companies named above, and no position in any of the subsidiaries or affiliates discussed. No position was opened, closed or changed in any security named in this article in connection with its publication. This article contains no price target, no recommendation and no view on whether any security discussed should be bought or sold.
Disclaimer: This article is for informational and educational purposes only and is not investment advice, a recommendation, or an offer to buy or sell any security. Market figures are as of the settled close of 22 September 2026 and financial figures as of the 30 June 2026 half-year report; both go stale quickly, and the June 2026 capital and asset-quality figures are marked provisional in the filing and may be restated. Disclosure of interest: the author holds a small long position in Hana Financial Group (086790), the subject of this article — one share, opened as a tracking position rather than a bet, and no price target or recommendation appears anywhere above. The author also holds Samsung Electronics (005930), which is named here, and KODEX 200, a KOSPI 200 index ETF that gives indirect exposure to all four bank holding companies discussed. The author holds no position in KB (105560), Shinhan (055550) or Woori (316140). Do your own research and consult a licensed adviser before investing.